Lugano has been acquired by private investment firm Middle West Partners and a group of the luxury jeweler’s clients, who joined the deal as co-investors, as the company seeks to move on from last year’s scandal.
The sale follows revelations of a multi-year accounting fraud and sham investment scheme orchestrated by founder Mordechai ‘Moti’ Ferder.
As part of the transaction, interim CEO Josh Gaynor has been appointed as the new chief and joined Lugano’s board of directors, effective immediately.
Gaynor previously held leadership roles at Bottega Veneta and Fendi before leading Bulgari North America’s high jewelry business.
“Together with our new ownership group, we have an exciting opportunity to build upon our client relationships, reinforce our values and continue raising the bar for the creativity, craftsmanship and personal service that define our brand,” Gaynor said.
Middle West Partners said it saw significant long-term growth potential in Lugano.
“Its loyal client base, talented team, and exceptional jewelry provide a strong foundation for continued growth,” said Kevin Kelleher, co-founder of Middle West Partners.
“We are excited to support Lugano through this transition, maintain the strength and continuity of its key management team, and further leverage Josh’s expertise in the luxury jewelry sector.”
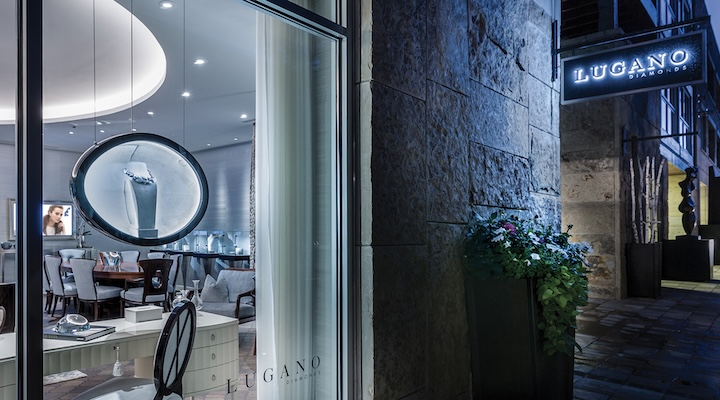
Lugano said its jewelry will continue to be manufactured at its Newport Beach, California, workshop, while its four existing boutiques will remain open.